The Gold Update by Mark Mead Baillie — 885th Edition — Monte-Carlo — 31 October 2026 (published each Saturday) — www.deMeadville.com
“Oh Woe Be Gold & Silver, but Whoa Are They Cheap!“
Ten completed trading months are now in the mix of 2026 as we go to our graphics-rich end-of-month tricks … for neither at this Halloween penning are there treats for Gold nor Silver.
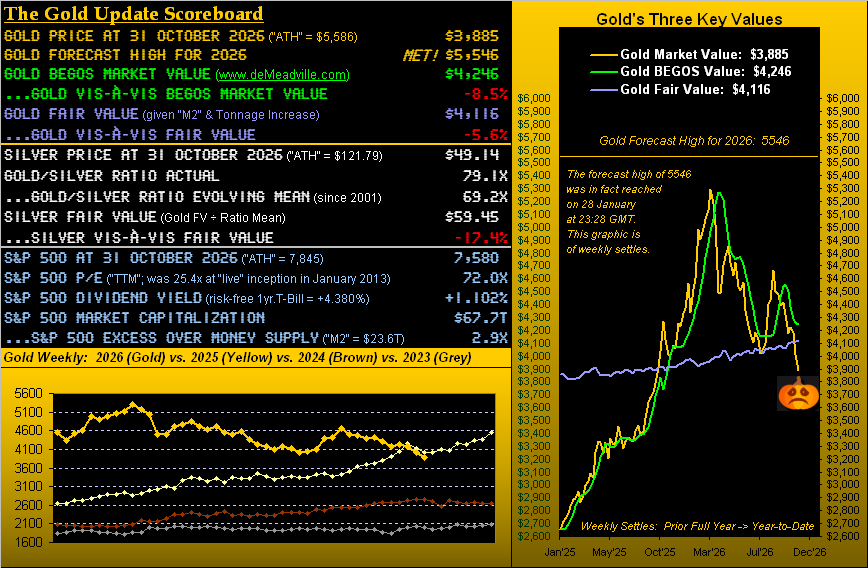
Gold settled October yesterday (Friday) at 3885, indeed down -30.5% from the 29 January (as back then repetitively-stated) way-overvalued All-Time High of 5586. But today, oh woe be Gold, and Sister Silver too! She, by comparison, in having closed the month at 49.14 is now -59.6% from her like January high of 121.78. Further, as herein concluded a week ago: “… the basing battle for ‘The Floor’ of Gold 4000 continues [and structurally] as long as the 3900s continue to hold, we’ll then anticipate the next upturn for Gold!” So far, that’s a “whoopsie!” there, given Gold having traded yesterday to as low as 3879.
“Well, there’s always the low overshoot, mmb…”
Still, Squire, one may have concern for another lurch lower. However: both Gold and Silver today are becoming well oversold. First fundamentally by Dollar debasement — directly from the above opening Scoreboard — we see Gold at now 3885 being -5.6% below Fair Value (4116) and Silver at 49.14 an attractive -17.4% below same (59.45).
“But over the years gold has traded much lower below fair value, mmb…”
Of course it has, dear Squire. For the four-year run from September 2011 into December 2015, Gold was regarded as a useless, valueless, scrap-metal relic. “Who the hell wants it? Get rid of it! It’s a storage pain in the ass! No, ya gotta go with S&P stars like Mallinckrodt and Perrigo and Kohls’ and CenturyLink and Endo and Macy’s and Alexian! They’re where it’s at, man!” (None of which today are in the S&P 500, if even around anymore).
But to Squire’s point, during that stint and then even up into COVID, Gold was trading in and around a -50% discount to Fair Value … which is why it necessarily rocketed (understatement) all the way back up and then some. Valued charter reader of The Gold Update THR is fond of saying “Gold will make you old”; but when priced beneath Fair Value, ’tis a no-brainer to own Gold as a long-term hold. Also, (as you need not be retold), Gold century-to-date at 3884 is +1,319% whereas the S&P 500 at 7580 is +768% including dividend reinvestment throughout. “Got Gold?” Further adversity notwithstanding, ’tis not a negative time to get some more — along with Silver whom we adore — given their Fair Value over time shall soar.
Too, technically, our combined textbook cocktail of Relative Strength, Stochastics and John Bollinger’s Bands finds both Gold and Silver now oversold through these last 25 trading days (from 28 September-to-date).
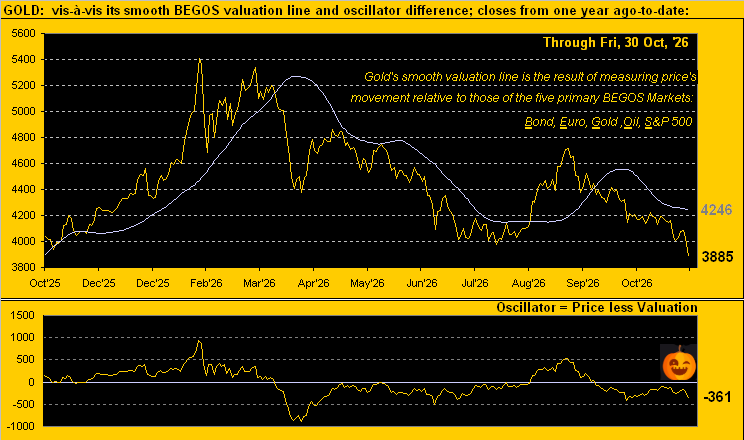
Then (again per the opening Scoreboard) we’ve Gold priced at a -8.5% discount to its BEGOS Market Value (4246). Yes, such deviation was far worse this past spring, yet let’s see if Gold can gather itself together here toward getting back above “The Floor” of 4000:
Either way, the negative conventional wisdom continues for Gold given the
“Hormuz Blues”
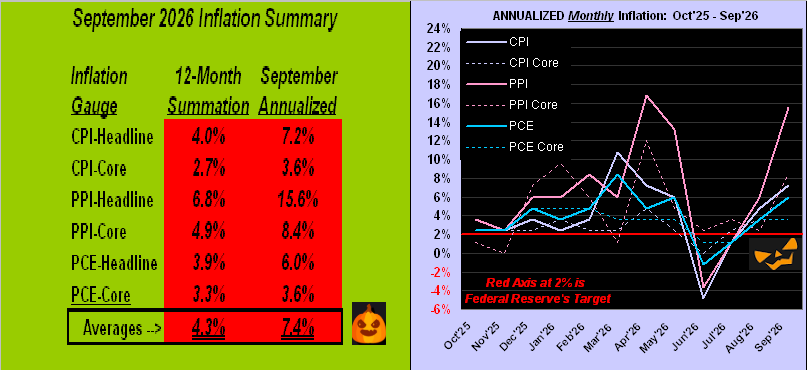
and the Federal Open Market Committee having to next consider a +50bp funds rate rise in their 09 December Policy Statement which would give the Dollar additional interest-rate appeal. For following the FOMC’s failure to raise +25bps this past Wednesday, the next day’s release of September’s Personal Consumption Expenditures completed our Inflation Summary which is nowhere near the Fed’s desired red-line inflation target of 2% per the two-panel graphic:
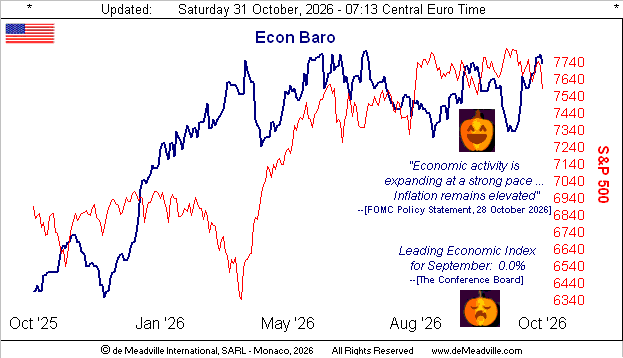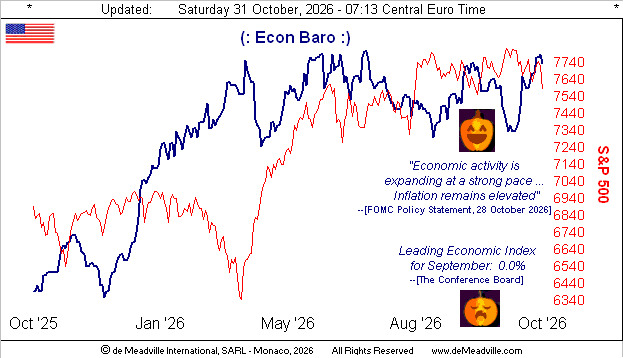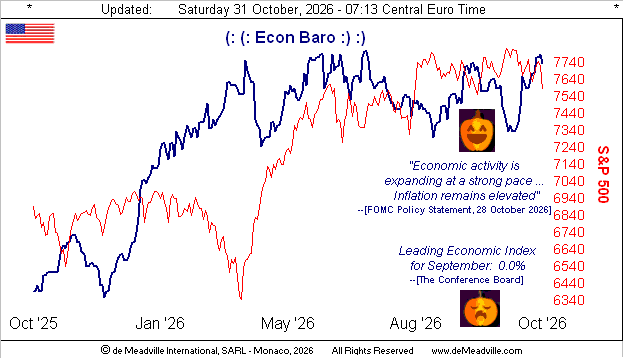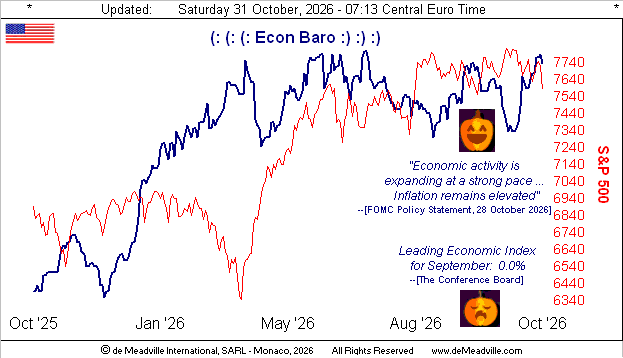
As to what the Fed said, here ’tis within the Economic Barometer, rather contra to that having just previously been stated by the Conference Board, leaving the S&P looking rather untoward:
That cited, we give hat-tips to FOMC members Cook and Hammack in solely voting on Wednesday for the Committee to have raised the Bank’s funds rate by +25bp; clearly they must follow our monthly Inflation Summaries.
“Yeah, but what about following gold’s trend, mmb…”
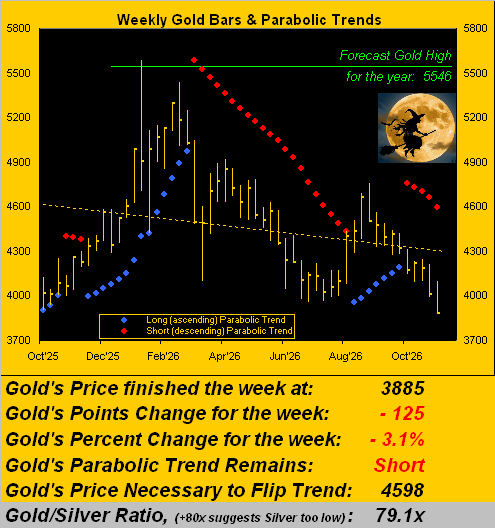
Squire, Gold has completed its fifth week of the red-dotted parabolic Short trend. From its trading commencement at 4169, price has declined (per yesterday’s low of 3879) by as much as -7.0%, which ranks second-worst across the prior 10 parabolic Short trends extending back to September 2022 … so put that in your year-over-year witch’s brew:
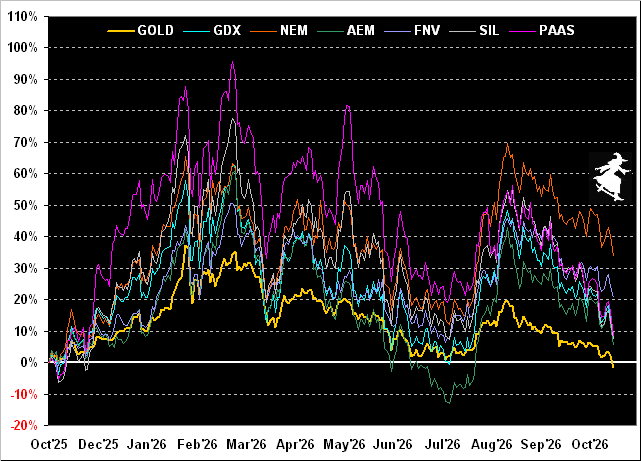
As to Gold astride her key equities brethren, per our view from a year ago-to-date, prices continue their down-skate, albeit Gold itself is the only percentage track in negative territory -1%. For the balance of the bunch from last October, we’ve Agnico Eagle Mines (AEM) +5%, the Global X Silver Miners exchange-traded fund (SIL) +7%, both Pan American Silver (PAAS) and the VanEck Vectors Gold Miners exchange-traded fund (GDX) +8%, Franco-Nevada (FNV) +21% and once laggard now leader Newmont (NEM) +34%. But to measure the percentage declines from late last February is far too scary:
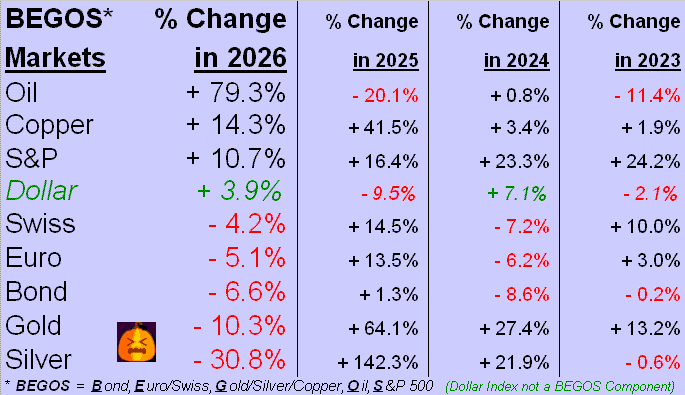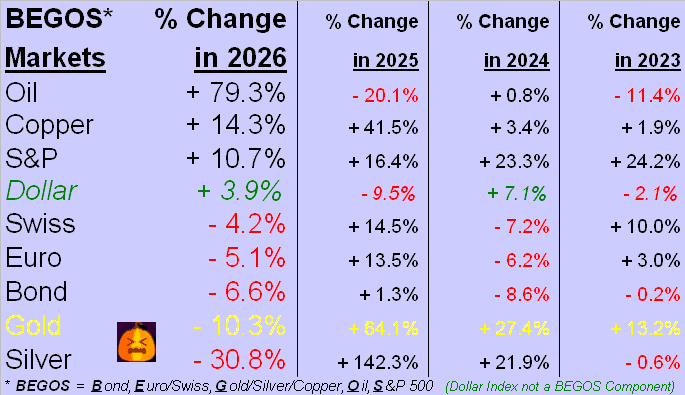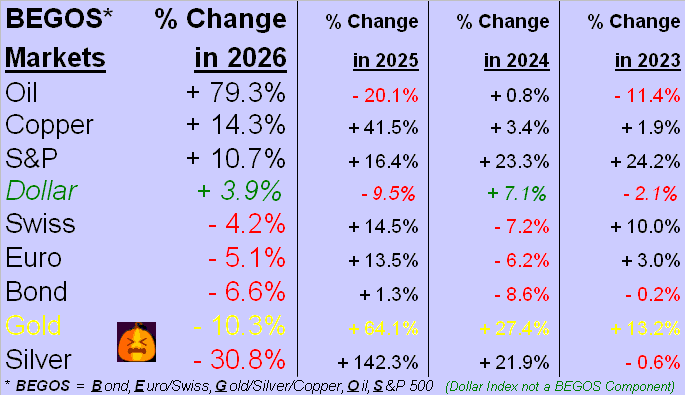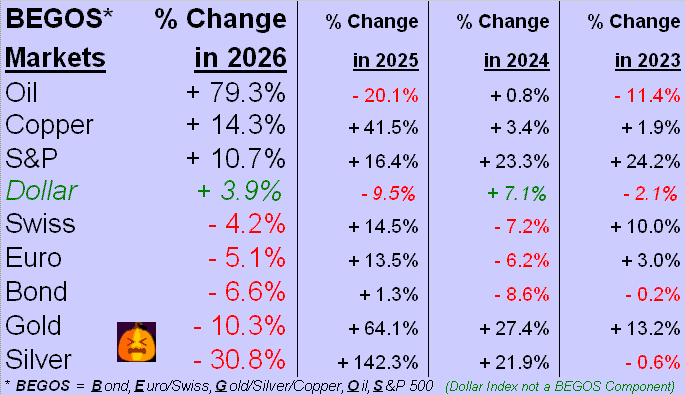
Scary as well are the BEGOS Markets Standings thus far for 2026: courtesy of the “From First to Worst Dept.” here they are. Fairly butt-ugly there for the precious metals after having dominated the podium throughout the early part of the year. Note therein the somewhat struggling S&P 500 still being up +10.7%; but if ’tis the beginning of the long-overdue great unraveling, by year-end shall such percentage still be black … or red? From its 06 October record 7845 high to yesterday’s 7528 low, the wildly-overvalued Index thus far has only -4.0% bled. What lurks for the S&P ahead? Best to hang on to one’s precious metals instead:
‘Course the burning Gold question (which in times of metals’ price strife makes the rounds) once again is: “How low is low?” Contextually, Gold having breached below our subjective barrier of 3900 to 3879 is — at least to this point — relatively immaterial. To give Gold a good news spin: its next zone of underlying structural support is significantly out-of-range from here that we don’t sense price going there, especially given the aforementioned already oversold measures. But for those of you scoring at home, “there” vis-à-vis “here” does appear as the 3400s, basically the centerpiece of Gold’s congested trading area from April into August a year ago. Plus seasonally, November-December is generally good for Gold: for the nine-year stint from 2017 through 2025, only once (in 2024) did Gold not settle the year above October’s close; moreover, through the 25 completed years so far this century, Gold has finished the year higher than ’twas for October 18 times. We thus again query: “Gold Gold?”
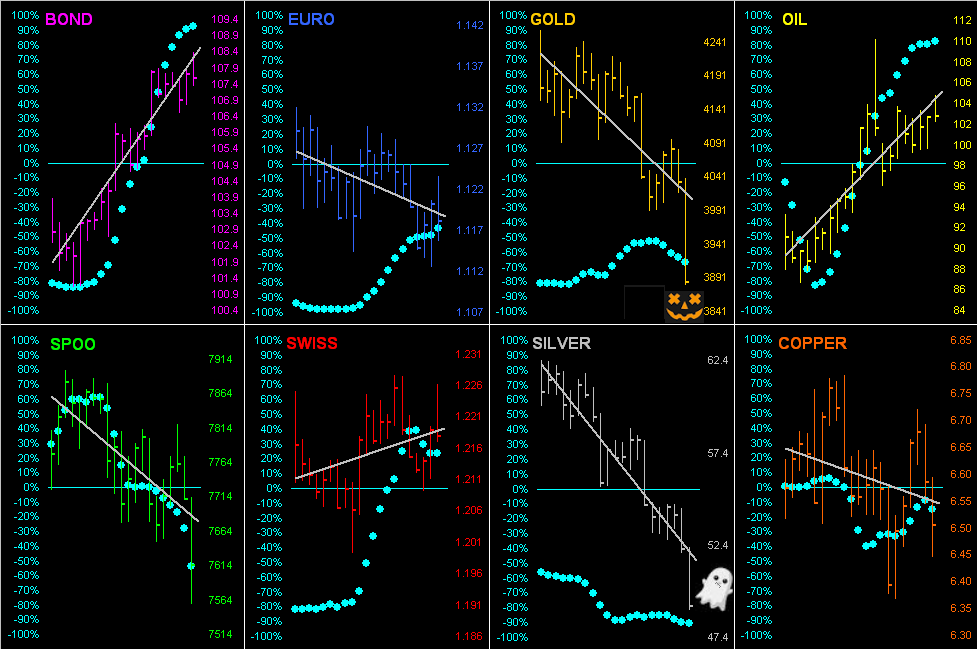
It being month-end, we next go ’round the horn for all eight BEGOS Markets per their last 21 trading days (one month), with the respective grey trendlines and “Baby Blues” which depict the day-to-day consistency of each trend. Clearly the Bond and Oil have been getting the bids, whereas Gold, Silver and the S&P (“Spoo”) have been on the skids:
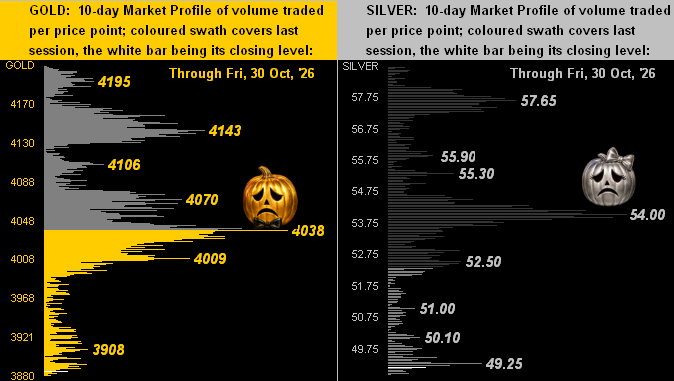
Thus hardly is today a “Happy Halloween” for the prescious metals in turning to their 10-day Market Profiles, featuring that for Gold on the left with same for Silver on the right. Yes Virginia, those wee white bars are October’s settles, prices having been mashed to the Profiles’ bottoms:
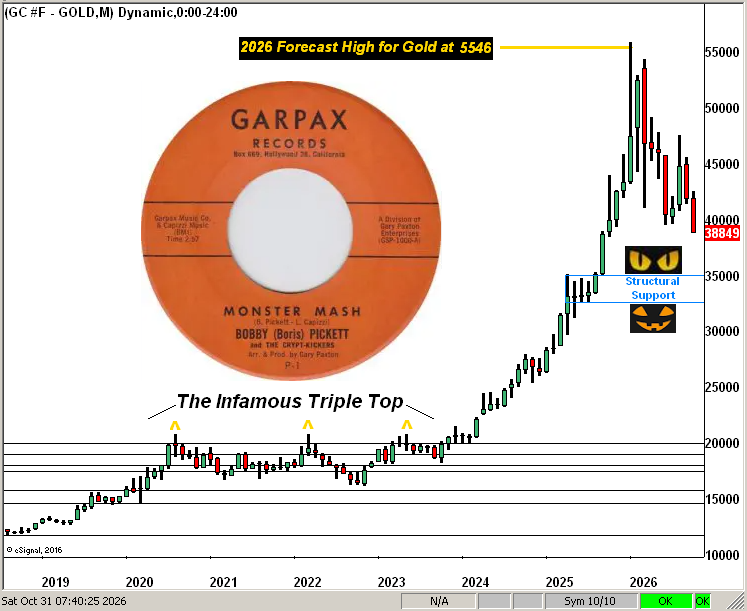
‘Tis therefore appropriate to next feature this hit which reached No. 1 on Billboard away back on 15 September in ’62 as we garnish Gold’s monthly structure since 2019. That rightmost candle for October marks Gold’s sixth down month in the last eight. No, it ain’t lookin so great, yet ’tis an opportunity to accumulate:
In sum, Gold is at a critical price area to hold toward regaining “The Floor” of 4000, which inevitably shall happen given Fair Value is up at 4116, (barring the Fed impossibly going on a money supply shrinkage binge). As usual, ’tis merely about “The When” and along what circuitous route of adversity Gold wends toward finding its northerly way, we trust without the 3400s structural support zone coming into play:

Now that’s the right way to go with Gold and Silver we say!
Cheers!
…m…
www.TheGoldUpdate.com
www.deMeadville.com
and now on “X”: @deMeadvillePro